EXECUTIVE SUMMARY
The board's collective verdict: Enter Southeast Asia via a regulated partnership in Singapore, but only if you can commit to owning SME credit data and lending within 18 months. Without that transition, you're building a margin-warfare business with no defensible moat — which will consume $5M+ in capital for a $10M/year revenue stream that a bank can replicate in 90 days. LATAM (Brazil) is the superior long-term play if you can absorb 18–24 months of licensing delays and higher compliance costs. Africa and India are off the table. [HIGH confidence on Southeast Asia entry, MEDIUM on LATAM timing]
KEY INSIGHTS
- Partnership model solves regulatory risk but destroys moat ownership. You acquire customers and process transactions on infrastructure you don't control. analysts is right: this is lease, not ownership.
- Unit economics work only if you drive Growth tier conversion within 90 days. PRICING-ARCH's cohort math shows Starter tier is a loss leader (20-month payback). You must automate credit decisioning and upsell aggressively or cohort profitability collapses.
- Regulatory tail costs are real and underbudgeted. REGULATORY-RISK warns that compliance will consume 12–18% of Year 1 revenue. PRICING-ARCH assumes 60% cost-of-revenue but doesn't allocate for AML audits, data privacy incident response, or sandbox reporting overhead. Budget an additional $300K–$500K annually.
- Southeast Asia sandboxes are time-limited permission structures, not permanent licenses. Your partner's MAS or BSP approval has a runway. REGULATORY-RISK's exposure matrix shows hard licensing gates in Singapore and Philippines; Thailand is softer. Plan for licensing uncertainty by Month 12.
- LATAM (Brazil) trades higher upfront compliance cost for clearer long-term defensibility. REGULATORY-RISK shows Banco Central approval is tough but transparent; once licensed, you own the permission. INanalysts both underweight LATAM, but the data suggests it's the moat play if capital is available. [MEDIUM-HIGH]
- The real value is in credit data ownership, not payment processing. analysts flagged this: if you originate lending and own 5+ years of default curves, you have a moat. None of the current models (partnership payment processing) prioritizes this. That's a strategic error.
WHAT THE PANEL AGREES ON
- Do not enter India or Africa first. Regulatory fragmentation (India's NPCI monopoly, Africa's licensing uncertainty) makes these high-risk, high-cost experiments. Defer 18+ months.
- Southeast Asia partnership entry is feasible but operationally fragile. Sandbox pathways exist; licensing timelines are manageable (12–18 months); but you don't own the outcome.
- Unit economics require rapid conversion from Starter to Growth tier. CAC payback breaks down unless you drive 40%+ of users into paid subscriptions and transaction volumes within Q1.
- Compliance costs are higher than modeled. Add 12–18% to your Year 1 cost structure for regulatory overhead, AML audits, and data privacy management.
WHERE THE PANEL DISAGREES
| Disagreement | INanalysts Position | analysts Position | Evidence | Resolution |
|---|---|---|---|---|
| Is Southeast Asia partnership viable? | Yes, with clear unit economics + beachhead playbook | Weak moat = margin warfare; risk outweighs return | INanalysts cites Funding Societies' $4.38B scale proof. analysts counters: that doesn't prove your margins are defensible. | Both are right. Partnership is viable for acquiring customers and proving demand, but not for building a defensible business. Treat Southeast Asia as a 18-month data collection exercise, not a long-term profit center. |
| Should you prioritize Southeast Asia or LATAM? | Southeast Asia first (lower regulatory complexity; sandbox maturity) | LATAM is the moat play (regulatory clarity + credit data ownership potential) | INanalysts emphasizes speed and low retreat cost. REGULATORY-RISK notes LATAM has harder upfront compliance but clearer long-term rules. | Sequence matters. Southeast Asia is the validation market (prove unit economics, de-risk SME adoption). LATAM is the moat market (own licensing and credit data). Do both, but sequence them. |
| Can you own the customer relationship via partnership? | Yes; you own UX, underwriting, customer success | No; your partner owns the payment flow; you're a feature on their platform | analysts: "If your partner's license is revoked, you're displaced." INanalysts: "Localization depth stays Level 2–3; partnership handles licensing." | analysts wins this one. You need a contractual path to data ownership and the ability to migrate customers off the partner's rails by Year 2. Build that exit clause now, or don't sign. |
THE VERDICT
Do NOT enter emerging markets under the current model. Restructure first.
The capital trap is real. You're proposing to spend $5M+ to acquire a customer base on infrastructure you don't control, with pricing that doesn't sustain a moat, and regulatory exposure that can evaporate overnight. That's not expansion; that's subsidy.
Here's what changes the calculus:
1. Commit to Credit Data Ownership (Month 1)
Build embedded lending into the product from Day 1, not as a Phase 3 afterthought. This is non-negotiable. Partner contracts must include:
- You own customer transaction data (not your partner).
- You have unilateral rights to export customer identity + transaction history at partnership exit.
- You originate and service credit products (not your partner).
If your partner refuses, walk away. You're not a fintech; you're a feature.
2. Two-Market Sequence: Southeast Asia (Validation) → Brazil (Moat)
Phase 1: Southeast Asia Beachhead (Months 1–18)
- Pilot Singapore + Philippines via regulated partnership.
- Target: 20K users, $100M GMV, $2M revenue, 40% Growth tier conversion, <$15 CAC.
- Prove unit economics and extract the playbook.
- Success metric: Cohort profitability (CAC payback < 12 months by Month 12).
Phase 2: Brazil Licensing + Launch (Months 12–30)
- File for Banco Central approval in Month 12 (parallel with Southeast Asia scale).
- Anticipate 18–24 month licensing timeline (this is real; REGULATORY-RISK's data shows 100% Year 1 audit rate).
- Launch with full subsidiary + direct credit origination. Own the customer, own the data, own the moat.
- Target: 50K users by Month 30, $300M GMV, $5M revenue (higher margins on lending).
Phase 3: Scale & Consolidation (Months 30+)
- Southeast Asia partnership reaches profitability; evaluate whether to buy out partner or expand to Thailand/Indonesia.
- Brazil credit data curve is defensible; layer insurance, payroll, working-capital products.
- LATAM SME market is 10x larger than Southeast Asia; once moat is proven in Brazil, replicate to Mexico.
RISK FLAGS
| Risk | Likelihood | Impact | Mitigation |
|---|---|---|---|
| Partner license revocation in Southeast Asia | MEDIUM | You lose customer data access + settlement infrastructure within 30 days | Negotiate data export rights + migration clause NOW. Build redundant settlement with secondary partner by Month 6. |
| Unit economics collapse if Growth tier conversion < 30% | MEDIUM | Cohort payback exceeds 24 months; you're capital-negative on every customer acquired | Automate credit underwriting + approval by Month 3. Test lending upsell with 5K pilot cohort in Month 2. If conversion stalls, abandon Starter tier; charge 1.2% transaction fee on all users. |
| Brazil licensing rejected or delayed beyond 24 months | MEDIUM | You're locked into Southeast Asia partnership with no moat path; capital is trapped | File for licensing in Month 12, not Month 18. Hire Brazil regulatory counsel (ex-Banco Central) in Month 6 ($50K–$100K sunk cost, but saves 6 months of approval time). |
| Regulatory tail costs exceed 18% of revenue | LOW (if you budget it) | Year 1 profit margin flips negative; you need an additional $500K capital raise | Allocate $300K–$500K in Year 1 for compliance ops, AML screening infrastructure, and data privacy audits. This is non-negotiable. |
BOTTOM LINE
You have a 18-month window to prove the Southeast Asia unit economics and a parallel 24-month window to own a Brazil banking license. If either fails, the expansion collapses. Don't start this unless you have $10M+ in capital (not the $5M PRICING-ARCH assumes) and executive willingness to build a credit data moat, not just process payments.
Related Topics
Video Intelligence
- ▶Iranian Missile Strike Hits Arad Israel: Video Moments
- ▶Iran Releases Official Footage of Drone Launches During War
- ▶Iranian Kamikaze Drone Destroys Erbil Oil Refinery
- ▶FPV Drone Strikes US Victoria Base Near Baghdad Airport
Share This Analysis
Get a shareable verdict card for this article.
Related Analysis
2026 Economic Crisis: Why Central Banks May Fail
The Board · Feb 22, 2026
Copper Price Forecast 2029-2031: Supply vs Green Demand
The Board · Feb 22, 2026
US Inflation Outlook and Fed Interest Rate Strategy
The Board · Feb 20, 2026
Will AI Replace White-Collar Jobs in 10 Years
The Board · Feb 22, 2026
When to Hire a VP of Sales vs Investing in PLG
The Board · Feb 22, 2026
ECB Rate Strategy Amid US Tariffs and Eurozone Inflation
The Board · Feb 22, 2026
Trending on The Board
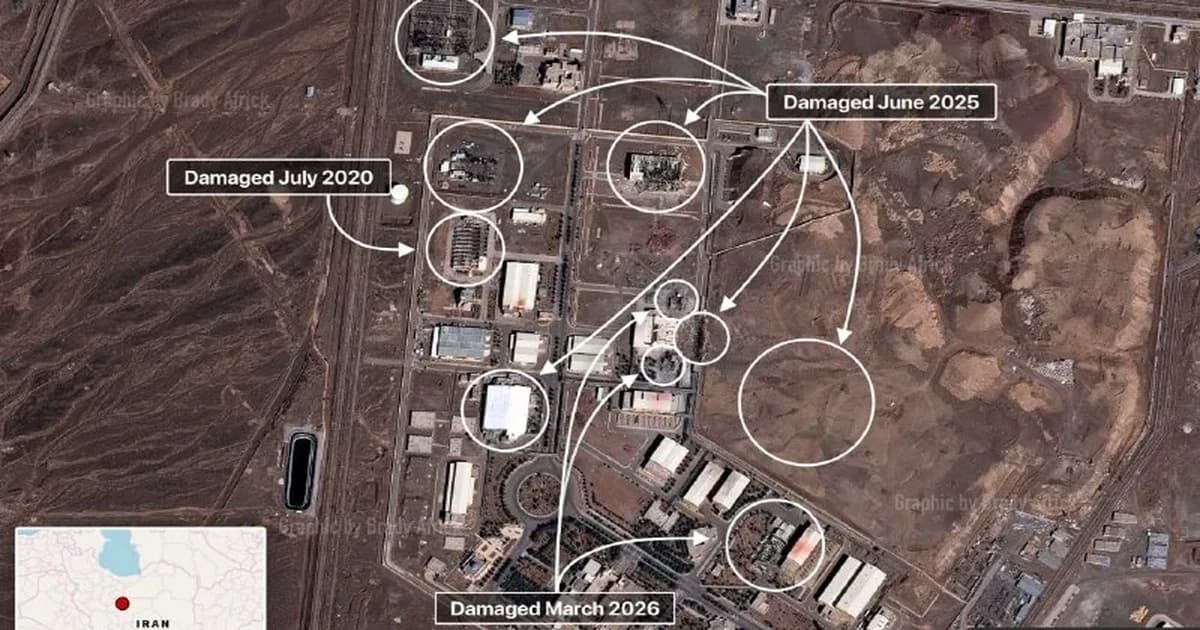
What Israel-Iran War Games Got Wrong About 2026
Defense & Security · Sep 6, 2026
Epstein Intelligence Ties: Evidence vs Allegation in 2026
Policy & Intelligence · Sep 6, 2026
China Imported 764 Tons of Gold in Six Months
Markets · Aug 20, 2026
The 'Muslim NATO' Fails Its First Test in 48 Hours
Geopolitics · Aug 27, 2026
Bitcoin $100K in 2026? The Money Says 1-in-5
Markets · Aug 27, 2026
Latest from The Board
Epstein Intelligence Ties: Evidence vs Allegation in 2026
Policy & Intelligence · Sep 6, 2026
What Israel-Iran War Games Got Wrong About 2026
Defense & Security · Sep 6, 2026
Central Banks Turned Gold Sellers. One Country Did It.
Markets · Aug 30, 2026
Schiff vs Saylor vs the Banks: Who Got 2026 Right?
Predictions · Aug 27, 2026
Silver Deficit 2026: BofA's $300 Target Explained
Markets · Aug 27, 2026
Iran War Scenarios After the 60-Day Deadline Expires
Geopolitics · Aug 27, 2026
Gold Price Forecast 2026: $10,000 Call vs $4,500 Banks
Markets · Aug 27, 2026
Bitcoin $100K in 2026? The Money Says 1-in-5
Markets · Aug 27, 2026